
, Fla. — For decades, retirement preparation can feel like a running calculation of how much to save, how much investments have grown and how much more is needed before leaving work.
But reaching a savings goal does not explain how that money will support everyday life when the paychecks stop.
For John Mouganis, a financial planner at Mouganis Financial Services, that transition calls for a different approach from the one people used to accumulate their savings.
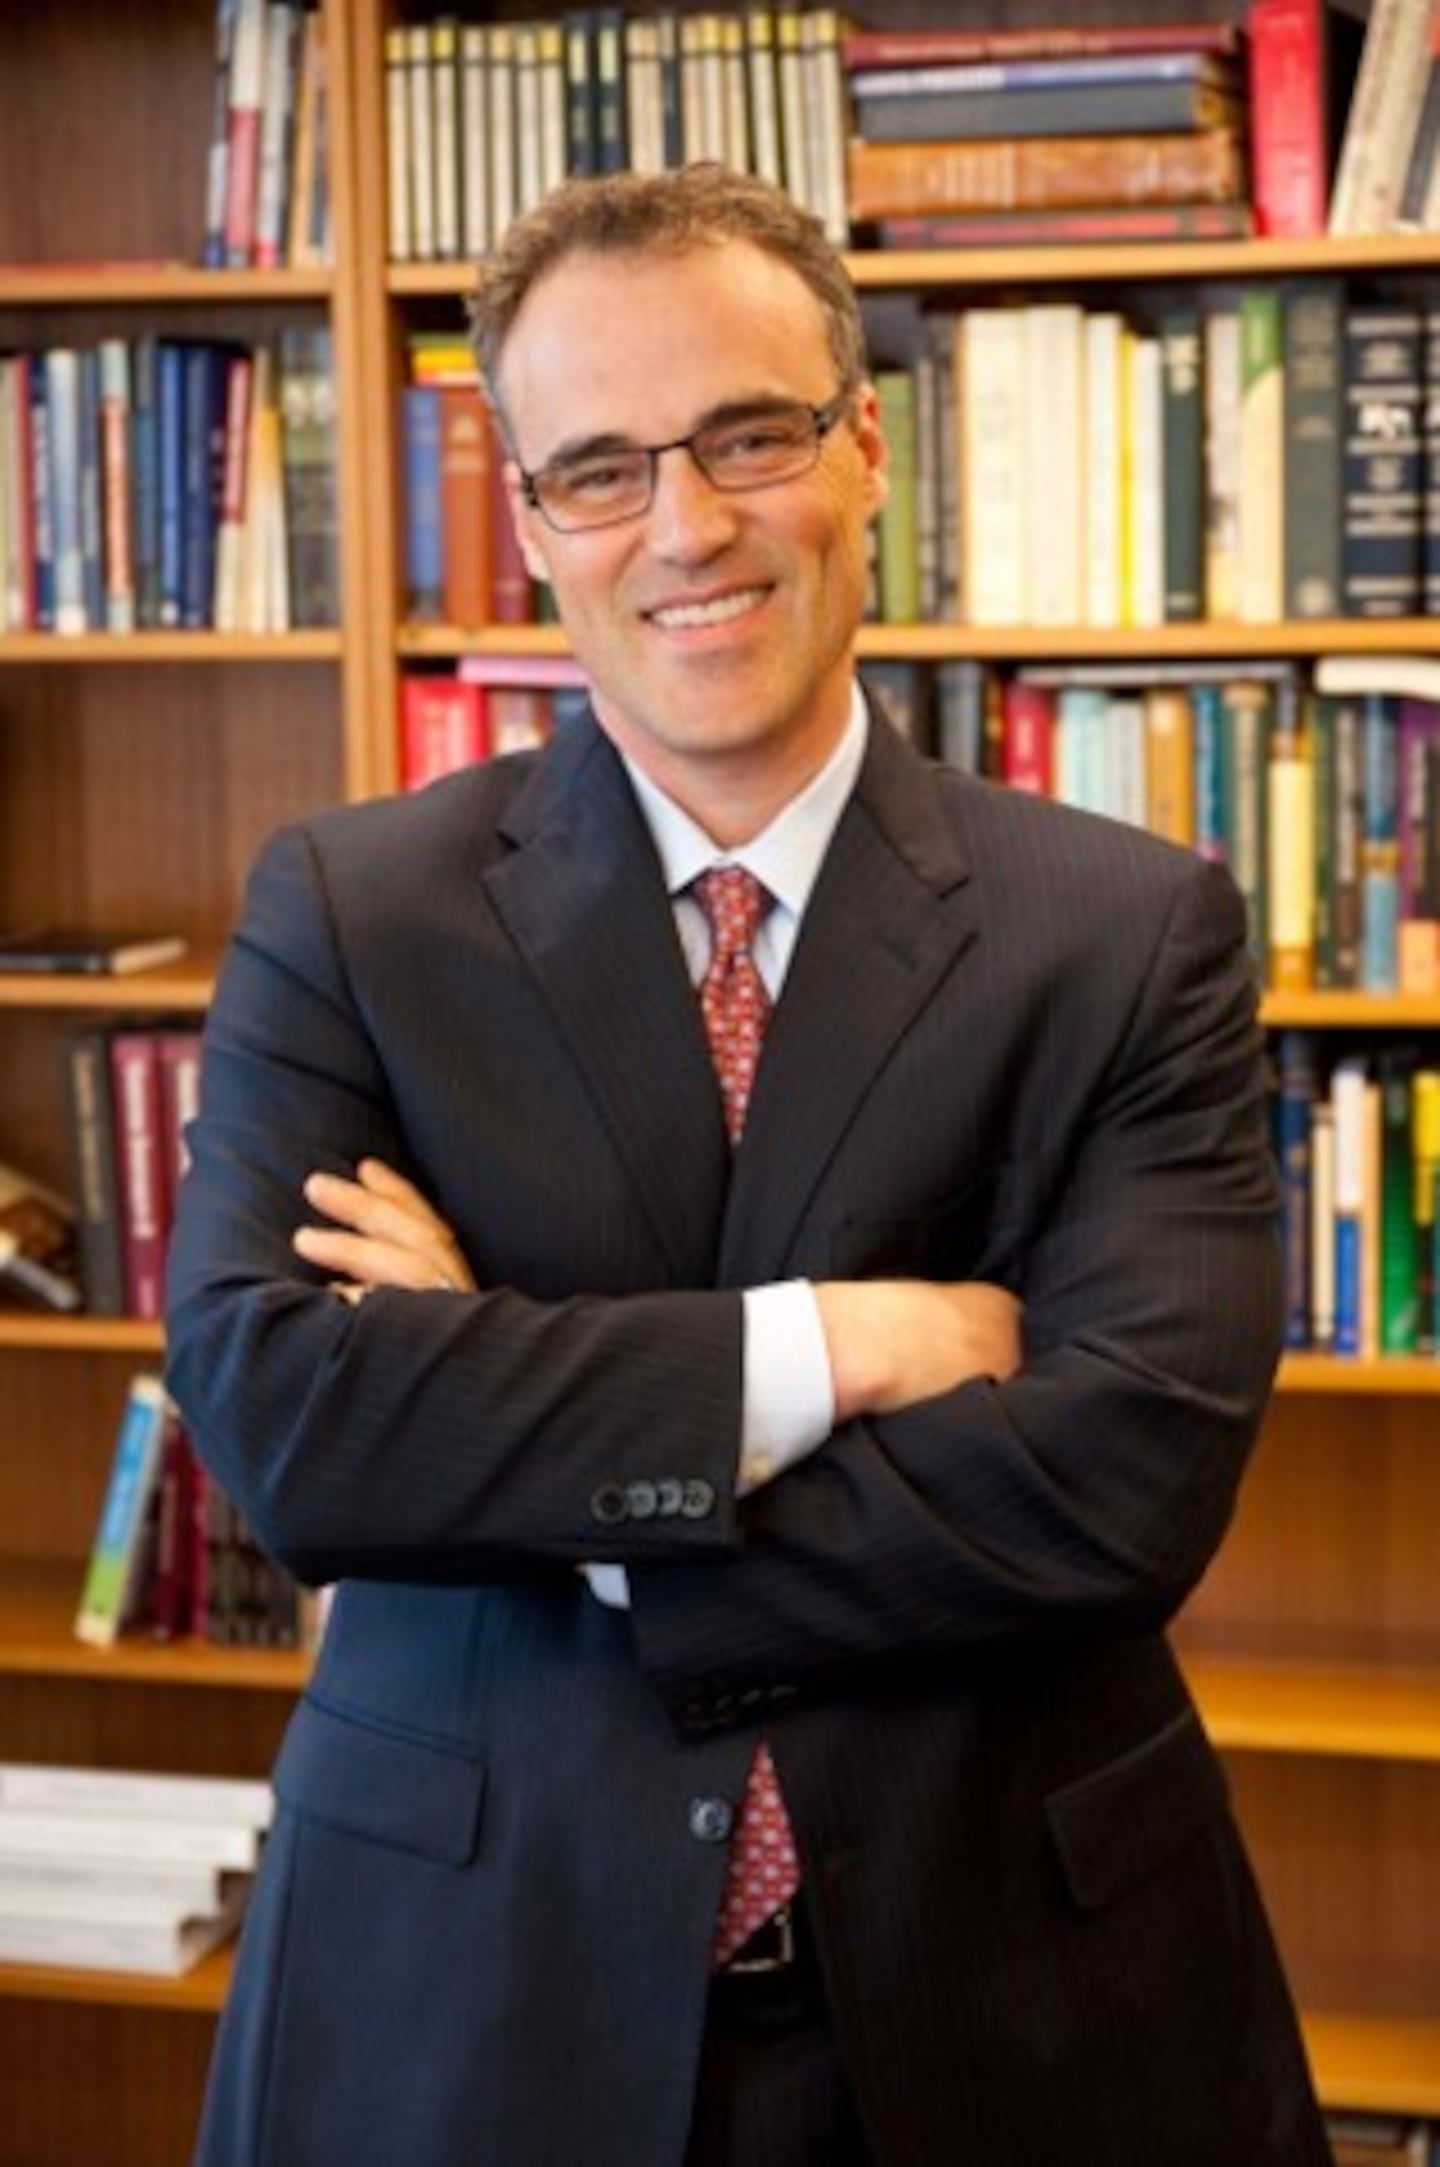
“Building wealth and living on that wealth require different skills and strategies,” Mouganis said in written interview responses.
His perspective draws partly on lessons from his father and his experience helping his own parents prepare for retirement. Those experiences, he said, made clear that retirement decisions involve more than investment performance. They also affect a family’s independence, responsibilities and ability to enjoy time together.
Lessons from Pittsburgh
Growing up in Pittsburgh in the 1970s, Mouganis learned about money from his father, a businessman who emphasized understanding the consequences of financial risk.
His father warned that market losses could arrive quickly and take years to recover from. The lesson was not to avoid investing, Mouganis said, but to recognize what a loss could mean before taking the risk.
Another lesson came through football. Mouganis said his father took him to the 1972 Pittsburgh Steelers playoff game remembered for Franco Harris’ Immaculate Reception.
The team’s combination of offense and defense became an analogy for his approach to retirement: Investments may need opportunities for growth, while resources needed for near-term spending require attention to risk.
Helping his parents navigate retirement brought those ideas into sharper focus.
“It’s one thing to talk about investment returns and financial projections,” he said. “It’s another when you’re thinking about your own parents, their financial security, their independence, their peace of mind, and their ability to enjoy their lives.”
When withdrawals change the equation
During working years, people may regularly contribute to investment accounts. In retirement, they begin drawing from those accounts to cover expenses.
That reversal changes how market declines affect a portfolio.
Someone withdrawing money during a downturn may have to sell investments at depressed prices. Those sales leave fewer assets available to benefit from a subsequent recovery, if one occurs.
Mouganis described this as sequence-of-returns risk: The timing of investment gains and losses, particularly when withdrawals begin, can influence how long savings last.
A retirement income plan therefore needs to consider more than an expected average return. It also needs to address when money will be needed, which accounts will supply it and how spending could change if markets disappoint.
FINRA’s retirement guidance similarly emphasizes managing withdrawals and being prepared to reduce discretionary spending after portfolio losses.
No withdrawal strategy eliminates investment risk. The appropriate approach depends on a household’s spending needs, other income sources and ability to adjust.
Start with the life the money must support
Mouganis said he prefers to begin retirement conversations with personal priorities rather than account balances.
That means asking how people want to spend their time, what responsibilities they expect to carry and what might make retirement meaningful. For couples, it also means ensuring both spouses understand the plan and have a voice in shaping it.
“I also encourage clients to think about what they want to become in retirement, not just what they want to do,” he said.
Work can provide structure, relationships and a sense of identity. Leaving it may require planning for those changes alongside the financial transition.
Those conversations help establish what savings must support, whether that includes travel, helping relatives, charitable giving or simply maintaining everyday routines.
“The investments should support the retirement plan,” Mouganis said. “The plan shouldn’t be built around the investments.”
Give different resources different jobs
Mouganis organizes retirement planning around liquidity, income, growth and preservation.
The distinction is practical: Money needed soon serves a different purpose from money intended for expenses many years away.
He said some households may benefit from organizing assets into time-based buckets. Others may focus on covering essential expenses with income sources such as Social Security and pensions before determining how investments will support additional spending.
Each approach involves trade-offs. Holding substantial cash may reduce the need to sell investments during a downturn, but it can also limit growth and leave purchasing power exposed to inflation.
For Mouganis, the objective is to help people understand how their spending will be funded rather than simply assign a portfolio a retirement label.
That clarity can matter psychologically, too. After decades of saving, some people struggle to spend even when they have substantial resources.
Leave room for things to go wrong
Mouganis also explores retirement risks in Retire On Your Terms, a book he contributed to.
His central question is straightforward: “Does everything have to go perfectly for your retirement plan to work?”
If the answer is yes, he said, the assumptions deserve another look.
A market decline could coincide with a health expense or a family emergency. Retirement could last longer than anticipated. A spouse’s death could change both household income and financial responsibilities.
Discussing those possibilities in advance allows people to consider potential adjustments before facing an urgent decision.
For people five to 10 years from retirement, Mouganis recommends connecting their desired lifestyle with expected income, spending and family obligations, then examining how the plan responds to setbacks.
“The closer you get to retirement, the more important it becomes to shift your focus from simply accumulating assets to understanding how those assets will support your life,” he said.
Click here to download our free news, weather and smart TV apps. And click here to stream Channel 9 Eyewitness News live.
©2026 Cox Media Group


